

Your top 20% know how to win deals, while the other 80% are guessing.
Your strongest performers carry your KPIs by running the same playbook on every deal, while you’re spending years (and money) trying to clone them. Meanwhile, across the rest of the team, deals stall, single-threaded with thin business cases and mutual action plans that don’t get actioned.
Accord makes your top performers’ playbook the whole team’s standard. Shaped by your unique sales process and real-time buyer conversations, Accord Agents handle the work between calls to move deals forward, so reps can focus on their buyers, and the conversations that close deals.
Accord brings agentic execution and the buyer experience together in one platform, turning how your best reps sell into how your entire team executes. Accord customers see an average 40% increase in deal size and 20% faster sales cycles.
Ready to be next? Visit inaccord.com
5 Charts on the AI Economy
Last week we shared three charts on where venture money is going. This week also shares charts, though across an adjacent topic: the AI economy itself.
These are five charts on token demand, AI spend, the infrastructure build-out, and how much room adoption still has.
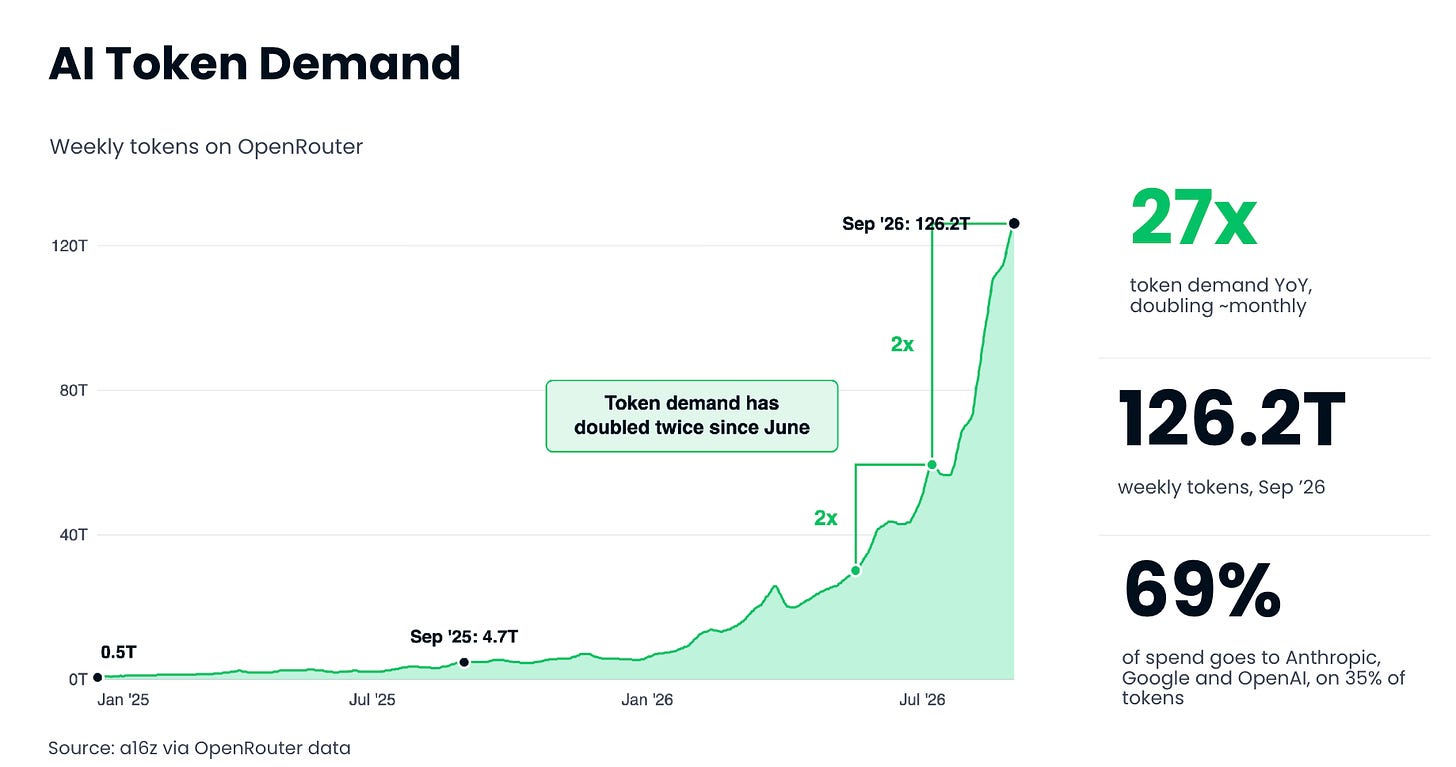
1. Token demand is up 27x in a year

Token demand on OpenRouter grew 27x year over year and is doubling roughly every month. Weekly volume reached 126.2 trillion tokens in September 2026, according to a16z’s analysis of OpenRouter data.
We wouldn’t be surprised if we did this 12 months from now and saw this graph be just as steep in 2027.
2. Frontier labs take ~70% of spend on 35% of tokens

Open and open-weight models now process about 65% of tokens on OpenRouter. Anthropic, Google and OpenAI handle the other 35%, but still capture roughly 70% of the spend. The lines for share of tokens crossed in 2026.
Total tokens are up 600x over two years. It is really important to underline this is not a zero-sum game. He expects both sides to keep growing, with more tokens running through open models and most of the spend still going to frontier labs.
3. Big Tech plans $700B in CapEx this year

Microsoft, Alphabet, AWS and Meta spent just over $100B on capex in 2023. Their 2026 plans add up to about $700B, according to Benedict Evans. For scale, that compares with roughly $300B for global telecoms and about $1T for oil and gas.
Analysts expect hyperscaler CapEx to pass $1T in 2027. We’re still supply-constrained on data centers, chips, energy and infrastructure, and the hyperscalers see underinvesting as their biggest short-term risk.
4. This doesn’t look like the dot-com bubble

Redpoint compared today’s AI build-out with the 2000 dot-com era:
- 2000: revenue lagged CapEx badly, the build-out was largely funded by debt, and fiber ran at under 3% utilization. Communications infrastructure CapEx topped $250B (inflation-adjusted), and the internet had 70M+ users about four years in.
- Today: OpenAI and Anthropic are each generating $50B+ ARR, the build-out is largely funded by cash flow, and more than 90% of capacity is pre-committed with near-zero data center vacancy. Hyperscaler data center capex is $700B+, and ChatGPT has 1B+ monthly users about four years in.
When you have this much capital entering the industry, you’re bound to have overinflation of certain assets… But does it look like the 2000 dot-com bubble? If you look at the data, not really.
5. Most industries are still early

Gallup tracked US workplace AI use by industry from June 2023 to December 2025, measuring any, weekly and daily use. Tech leads. Healthcare, manufacturing and government, each a trillion-dollar industry, report about 25% weekly use.
There’s still so much growth to be had.
The bottom line
Token demand is up 27x in a year, most of the spend still goes to frontier labs, and the build-out is largely funded by real revenue. Adoption in healthcare, manufacturing and government is still early.
Which of these surprised you most? Let us know in the comments.
Tag @GTMnow so we can see your takeaways and help amplify them.
More for your eyeballs
Tomasz Tunguz ran Anthropic’s S-1 through his 7 key metrics. Revenue grew 11.9x to $4.6B in 2025, Anthropic posted $974M of operating profit in Q2 2026, and it holds $637B in compute commitments. Nearly half of revenue now flows through cloud marketplaces.
Jamin Ball benchmarked Anthropic’s S-1 against public software companies. Anthropic did $19B+ in LTM revenue, grew 1,368% year over year in Q2, and ran 85% gross margins and 21% FCF margins over the six months ending June 30.
Foundation Capital’s Jaya Gupta argues AI’s next economy runs on execution. Written with Ashu Garg, the piece bets that owning the most GPUs will stop guaranteeing the most value, as apps buy a changing mix of frontier inference, smaller and open-weight models, and execution services.
Noble reviewed 23 studies on AI search. Between 75% and 85% of AI citations come from third-party and competitor sites, so a brand is 6.5x more likely to surface through someone else’s content than its own. And 56% of AI-driven demand shows up as branded search, not direct referrals.
Andrew Chen mapped 5 new founder archetypes for the AI age. His list: solo founders, non-technical founders, domain experts, young founders and creators with built-in audiences.
More for your eardrums
GTM: Inside Exa’s Run to $100M ARR: Building Google for AI Agents | Marcus Holm, Exa
Listen through the links in the page above or by searching wherever you get your podcasts “The GTMnow Podcast.”
Startups to watch
Omnichat – raised a $10M Series A led by Openspace Capital for AI marketing, sales and service agents that work inside messaging apps. It serves 5,000+ brands including Dyson, FILA and L’OCCITANE across WhatsApp, LINE, Instagram, WeChat and TikTok. About 300 brands adopted its OmniClaw analytics agent within two months of its June launch.
Qualitate – raised a $25M Series A led by Insight Partners for AI that runs expert interviews and turns them into structured research. Insight was a customer before leading the round. Qualitate says its revenue run-rate grew more than 10x in the past year, with 12-month net revenue retention above 300% and over 1M minutes of AI-moderated interviews. Customers include UiPath, Collibra, Alteryx and Commvault.
Hyphenate – raised a $45M Series A led by Nexus Venture Partners for autonomous finance agents built for the office of the CFO. B Capital, Foundation Capital, BoldCap and Gaia Ventures also participated. Revenue grew 86x over the past year, and customers grew 11x to include six public companies, Groupon among them.
Hottest GTM jobs of the week
- Head of GTM at BlueCargo (New York, NY)
- GTM Program Manager, Revenue Onboarding at Vanta (Remote – US)
- Enterprise Sales Lead, Northeast at Esper (Remote – Northeast US)
- Head of Technical Solutions at Gorgias (Toronto, Canada)
- Technical Implementation Manager at Crossbeam (Remote – US)
See more top GTM jobs on the GTMfund Job Board.
GTM industry events
Upcoming events you won’t want to miss:
- GTMfund Toronto Dinner: November 16, 2026 (Toronto, Canada)
- GTMfund NYC GTM Leader Happy Hour: November 18, 2026 (NYC, NY)
GTMnow community love
Some GTMnow Network love to close it out – we appreciate you.